First-Time Buyers
How Much House Can I Afford in Florida?
 Ian Anderson · NMLS ##1849097
How much house can I afford in Florida?
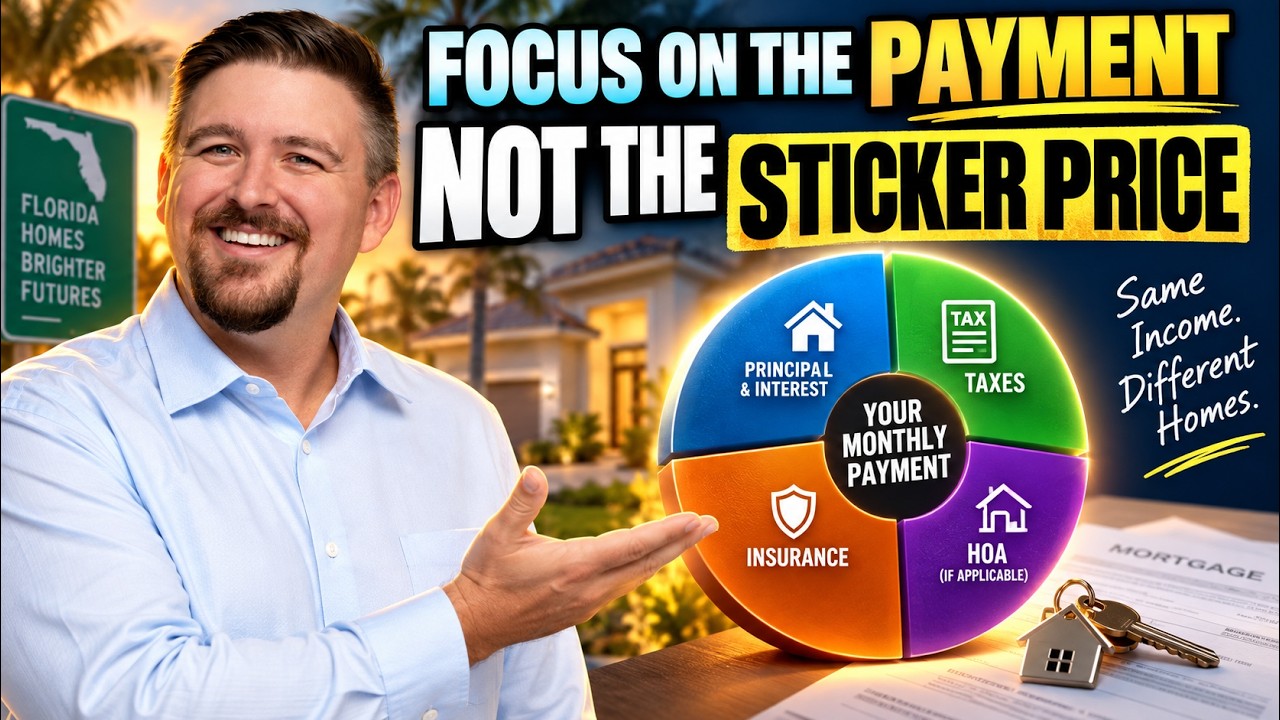
In Florida, your income doesn't directly decide how much house you can afford. Your monthly payment does. Lenders look at your full PITI payment (principal, interest, taxes, insurance) plus HOA and CDD fees, then compare it against your income and existing debts through your debt-to-income ratio. Two buyers earning the same amount can qualify for very different homes once these costs are factored in.
In Florida, your income doesn't directly decide how much house you can afford. Your monthly payment does. Lenders look at your full housing payment, principal, interest, taxes, and insurance, plus HOA and CDD fees, then compare that against your income and existing monthly debts. Two buyers earning the same salary can qualify for very different homes once all of these costs are factored in.
Why do two people with the same income qualify for different homes?
Picture two buyers who both earn about $100,000 a year and even share the same job title. One might comfortably afford a home near the $400,000 range. The other might be closer to $280,000 with that same income. The difference usually isn't their paycheck at all. It's everything happening around that paycheck.
This is the biggest thing people get wrong when they try to figure out how much home they can afford in Florida. You've probably tried one of those online affordability calculators. You plug in your income and down payment, and a few seconds later it tells you that you can afford some very specific number. The problem is that calculator doesn't know nearly enough about you or the property you're buying to give you a truly useful answer.
Why does your monthly payment matter more than your income?
Your income is part of the equation, but the real question is how large of a housing payment fits into your financial picture. Once you look at it that way, this gets much easier to understand.
When mortgage professionals talk about your housing payment, you'll hear the term PITI. That stands for principal, interest, taxes, and insurance. Principal is the part of the payment that pays down what you borrowed. Interest is what you pay for borrowing the money. Then you have property taxes and homeowners insurance. Those four things combined are much closer to your real monthly housing cost.
A lot of calculators show you a principal and interest payment that looks great, but that isn't necessarily what leaves your bank account each month. In Florida, those extra costs can make a big difference.
How does homeowners insurance affect what you can afford in Florida?
Insurance has been one of the biggest surprises for Florida homeowners over the last several years. Premiums have gone up a lot, and the cost depends on the home's location, the age of the roof, how close it sits to the coast, and other factors. Two homes with the exact same purchase price can carry very different insurance premiums.
Imagine comparing two homes at the same price. One is inland with a newer roof. The other sits closer to the water with an older roof. Same price, same down payment, same buyer, but the monthly payment could be completely different. That's why the type of home and its location changes the math. The good news is that Florida's insurance market has shown some improvement, with several carriers filing rate decreases, but insurance is still something you have to plan for.
What Florida-specific costs catch buyers off guard?
Property taxes. Florida has a relatively low effective property tax rate, though it varies quite a bit by county, exemption, and individual property. Even so, that expense adds real dollars to your monthly payment. You can learn more about how property is assessed through the Florida Department of Revenue.
CDD fees. Community Development District fees show up often in newer master-planned communities. The developer finances roads, infrastructure, and amenities through a bond, and homeowners repay it through the property tax bill. Depending on the community, that can add a meaningful amount every month. You might walk into a beautiful model home, fall in love with the neighborhood, and then discover an extra charge sitting on the tax bill.
HOA fees. If you're looking at a condo, town home, or many newer single-family communities, you may have a homeowners association. From a qualification standpoint, that HOA payment counts against your budget too.
Add taxes, insurance, HOA, and CDD fees together and the real payment can be hundreds of dollars higher than the mortgage alone suggested. That's why you should focus on the payment, not just the price of the house.
How does debt-to-income ratio change your budget?
Lenders don't just care how much you make. They care how much of that income is already committed elsewhere. That's your debt-to-income ratio, or DTI. The idea is simple: how much money comes in each month, and how much of it already has somewhere to go.
Go back to our two buyers earning $100,000. Buyer one has no car payment, no student loans, and very little monthly debt. Buyer two has a truck payment and a student loan payment that together take a big bite out of every month before a house even enters the picture. That committed money could otherwise go toward the housing payment. This is exactly how two people with the same income qualify for very different purchase prices.
It's also why quick rules like "multiply your income by three" don't work well. That shortcut ignores your debts, taxes, HOA fees, insurance, down payment, and interest rate. The Consumer Financial Protection Bureau explains how these pieces fit together when you plan a home purchase.
How do interest rate and down payment change the math?
When mortgage rates move, your monthly payment moves with them. Even a small rate difference can change the payment on the same house, and when the payment changes, so does the price you can comfortably afford. Your actual rate depends on things like your credit, your down payment, the property, and the loan program you choose.
Your down payment matters too. The more you put down, the less you borrow, and the lower your principal and interest payment. A larger down payment can either help you afford a more expensive home or give you a more comfortable payment on the same one. And you do not necessarily need 20% down. Depending on your situation and loan program, there are options that require significantly less.
Does the loan program affect how much home you can afford?
Yes. FHA, conventional, and VA loans each have their own guidelines, and the right program can change your down payment, mortgage insurance, qualifying ratios, loan limits, and monthly payment.
FHA loans can allow as little as 3.5% down for borrowers who meet the requirements. Conventional loans also offer low down payment options for qualifying buyers. Eligible veterans and active-duty service members may use VA financing, which changes the equation again. You can review VA benefits through the U.S. Department of Veterans Affairs. Fannie Mae also offers a helpful Mortgage Affordability Calculator to explore ranges.
What's the difference between what you're approved for and what you can afford?
There are really two numbers here. The first is the maximum a lender will approve you for. The second is the payment you can comfortably make every month while still enjoying your life. Those two are not always the same.
A payment can technically work on paper without being a payment you actually enjoy making. Maybe you like to travel, maybe you have kids, maybe you want to keep investing. A calculator and an underwriting system don't know any of that. A good approach finds a range that fits your life instead of just the biggest number possible.
Find your real Florida home budget
So the real question isn't "I make $100,000, how much house can I afford?" It's "I make this much, I have these debts, this much for a down payment, I'm shopping in this area for this type of home using this loan program, so what payment actually makes sense?"
If you want your real number, request your personalized home buying budget here. We'll look at your income, monthly debts, credit, down payment plans, and where you're buying, then run actual numbers that account for taxes, insurance, HOA, and CDD costs. If you're not ready yet, subscribe to the channel for weekly breakdowns of mortgages, home buying, and the Florida housing market.
Frequently asked questions
How much house can I afford in Florida on a $100,000 salary? +
It depends far more than most people expect. Two buyers earning $100,000 can afford very different homes because of their existing debts, down payment, interest rate, and the property's taxes, insurance, HOA, and CDD costs. One buyer with no debt might comfortably afford a home well above another buyer carrying a truck and student loan payment. Instead of relying on a simple income multiple, look at what monthly payment fits your full financial picture and then work backward to a purchase price.
What is PITI and why does it matter in Florida? +
PITI stands for principal, interest, taxes, and insurance. Principal pays down what you borrowed, interest is the cost of borrowing, and taxes and insurance are added on top. In Florida, insurance premiums and property taxes can vary a lot by location, roof age, and proximity to the coast. Many online calculators only show principal and interest, which understates your real payment. Your true monthly housing cost includes all four PITI parts plus any HOA or CDD fees.
What are CDD fees in Florida? +
CDD stands for Community Development District. In many newer master-planned Florida communities, the developer finances roads, infrastructure, and amenities through a bond. Homeowners repay that bond through their annual property tax bill, which can add a meaningful amount to your monthly cost. Buyers often fall in love with a model home and later realize a CDD charge sits on the tax bill. Always ask whether a community has CDD fees before setting your budget.
Do I need 20% down to buy a home in Florida? +
No. That's a common misconception. Depending on your situation and loan program, you may qualify with far less. FHA loans can allow as little as 3.5% down for eligible borrowers, conventional loans offer low down payment options for qualifying buyers, and eligible veterans or active-duty service members may use VA financing with no down payment. A larger down payment lowers what you borrow, but it isn't required to buy.
How does debt-to-income ratio affect affordability? +
Your debt-to-income ratio, or DTI, compares how much money comes in each month to how much already has somewhere to go. Car payments, student loans, and other monthly obligations reduce the income available for a housing payment. That's why two buyers with identical incomes can qualify for very different homes. Paying down monthly debts before you buy can increase your buying power, even without a raise.
Sources
- Mortgage Affordability Calculator — Fannie Mae
- Owning a Home — Consumer Financial Protection Bureau
- VA Home Loans — U.S. Department of Veterans Affairs
- Property Tax Information for Taxpayers — Florida Department of Revenue
About the author
Ian Anderson — President / Sr. Loan Advisor
NMLS ##1849097
Ian Anderson is the founder of Fisherman Mortgage Services, a Tampa Bay-based brokerage licensed in Florida, Georgia, and Wisconsin. A top 1% loan officer, he serves buyers across Tampa, St. Pete, and Bradenton with an education-first approach: know more, borrow better.
Ready to talk numbers?
Schedule a 15-minute call. We'll walk through your situation and show you what's actually possible — no pressure, no pitch.
Book a call